

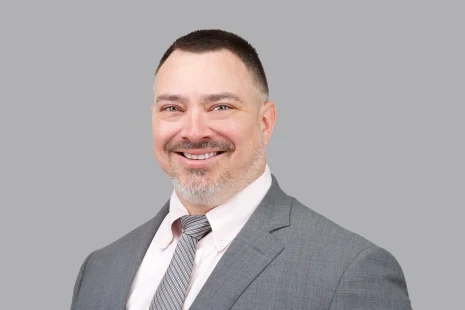
Kenneth E. Burdon
Partner, Simpson Thacher & Bartlett LLP
FOUNDED
1884
HEADQUARTERS
New York
STRUCTURE
Private partnership
REGISTERED FUNDS BENCH
160+ lawyers
INDUSTRY EXPERIENCE
30+ years
PRACTICE FOCUS
Registered Funds
THE FIRM
About Simpson Thacher
Simpson Thacher & Bartlett LLP has been advising the closed-end fund, BDC and interval fund industry for more than three decades. The Firm’s roots go back a lot further than that. Founded in 1884 and headquartered in New York, Simpson Thacher is a law firm whose clients include many of the world’s leading asset managers, investment funds, financial institutions and public companies.
As legal counsel rather than an asset manager, the Firm doesn’t run funds or manage capital directly. Its job is advising the sponsors who do, on everything from product structuring to regulatory strategy.
Simpson Thacher has more than 160 lawyers dedicated to registered funds.
THE PRACTICE
Where the Firm Does Its Best Work
That advisory role has put Simpson Thacher at the center of some of the registered fund industry’s most significant launches. The Firm has worked on many of the market’s most innovative closed-end funds, BDCs, interval funds and other products that provide retail access to private markets, and points to repeat-client relationships as the clearest evidence of that track record.
Simpson Thacher’s client base spans the full range of registered fund sponsors. The Firm describes its strongest work as helping market leaders shape the next generation of investment products: expanding retail access to private markets through registered fund structures, and developing first-of-their-kind structures as the industry evolves. Right now, that means a heavy focus on the retailization of private credit, private equity and other alternative strategies offered through registered wrappers, a trend the Firm expects to keep driving product innovation across the sector.
“
We’ve been at the forefront of developing first-of-their-kind registered fund structures that expand retail access to private markets, and we help sponsors not only navigate the legal framework but build innovative products that can succeed over the long term.
KENNETH E. BURDON, PARTNER
THE COMMUNITY
Why AICA
Q What drew you personally to registered funds law? Was there a specific deal, mentor, or moment early on?
Simpson Thacher joined AICA because the organization gives industry participants a forum to exchange ideas, discuss regulatory developments and build a broader understanding of closed-end funds, BDCs and interval funds, a mission the Firm says aligns with its own commitment to education and engagement across the investment community. Looking ahead, the Firm expects to keep advising clients through the convergence of traditional and alternative asset management, helping sponsors develop new products and navigate an increasingly dynamic regulatory and market environment.
THE CONVERSATION
Q&A with Kenneth E. Burdon, Partner
Q What drew you personally to registered funds law? Was there a specific deal, mentor, or moment early on?
I didn’t start out thinking I wanted to be a registered funds lawyer. In fact, I was mostly interested in doing M&A. However, when I was a summer associate, the M&A deal I worked on involved the acquisition of an investment adviser, and I was more interested in the investment adviser regulatory aspects of the transaction. So, I acted on that, indicated I’d be interested in working in the registered funds group when I returned and focused more on this area when I went back for my last year of law school. When I returned as a first year associate, I started doing registered funds work and liked it. During that time, I continued to build on my knowledge and skillset. Fun fact: I was a first-year associate in 2007, and the first fund I was counsel to was an interval fund. It has been quite the round trip I’ve taken, with interval funds again being an important part of the CEF growth story.
FULL CIRCLE
Burdon was a first-year associate in 2007, and the first fund he served as counsel to was an interval fund, a structure now central to the closed-end fund growth story.
Q Outside of work, what’s something people would be surprised to learn about you, or what do you do to unwind?
My hobbies include strength training, collecting vintage baseball cards and collecting coins. The coin collection is actually quite interesting and has been in my family for almost 200 years. It was started by my great-great-great-grandfather in the mid-19th century, and has been passed on from generation to generation. I work on it from time to time with my 12-year-old son.
Q What’s the most valuable thing AICA membership has given your practice? The relationships, the regulatory dialogue, something else?
For me, as a lawyer, AICA has been a great venue to read, hear and understand the investment professional’s perspective on the products that I help to create, care for and feed. It also offers beneficial insight into what it is about those products that they value. And it is the diversity of that perspective that I appreciate the most. Having that perspective has helped me to be a better counselor to my clients because understanding the legal framework is only one piece of the puzzle.
FOR FUND SPONSORS
For fund sponsors weighing counsel on their next closed-end fund, BDC or interval fund launch, or navigating a structural change on an existing one, Simpson Thacher’s decades of repeat-client work across the space is worth a conversation.
Learn more at stblaw.com, or contact Kenneth E. Burdon at
kenneth.burdon@stblaw.com / +1-617-778-9001.
DISCLOSURES
Important Information
This Member Spotlight is provided by the Active Investment Company Alliance (AICA) for informational and educational purposes only. It does not constitute legal, tax, or investment advice, and it should not be relied upon as such. Readers should consult their own qualified counsel regarding their specific circumstances. No attorney-client relationship is created by reading this profile or by contacting the firm featured in it.
The views and opinions expressed are those of the featured individual and firm and do not necessarily reflect the views of AICA. Information about the firm, including statements about its experience, practice, and client relationships, was provided by the firm and has not been independently verified by AICA. AICA does not endorse, recommend, or guarantee the services of any member firm.
References to closed-end funds, business development companies, interval funds, or other investment products are for general industry context only and are not an offer to sell, a solicitation of an offer to buy, or a recommendation of any security.